Debt Consolidation: Is it the Ultimate Personal Finance Game-Changer or a Danger Zone?
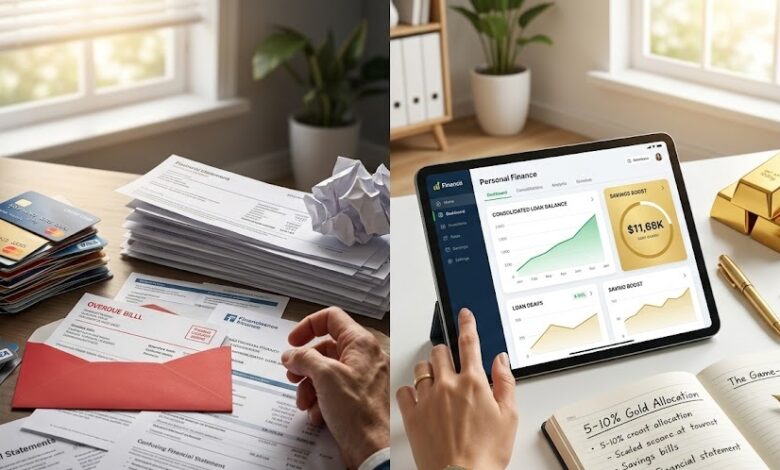
In the complex world of personal finance, debt is often the heaviest anchor. Carrying multiple high-interest debts—from credit cards and personal loans to medical bills—is not just financially draining; it is mentally exhausting. Every month brings a chaotic puzzle of different due dates, payment amounts, and interest rates. Debt consolidation promises a solution: simplifying your financial life by combining all your debts into a single, manageable monthly payment, often with a lower overall interest rate. On Finance Shoot, we analyze the data. Is debt consolidation the game-changer that sets you free, or is it a hidden danger zone that can make things worse? The answer depends entirely on your strategy.
The Mechanic: How Debt Consolidation Works
At its core, debt consolidation is a simple strategic swap.
-
The Process: You take out a new loan (usually a fixed-rate personal loan) that is large enough to pay off all your current high-interest, unsecured debts.
-
-
The Swap: Instead of paying five different creditors at varying high rates (e.g., 20%+ on credit cards), you now have one loan, with one creditor, and one fixed interest rate (ideally significantly lower, e.g., 8-14%).
The Benefits: Clarity, Savings, and a Score Boost
When done correctly, debt consolidation offers immediate personal finance relief.
-
Financial Clarity: You replace multiple payments and dates with one single monthly payment. This simplifies budgeting and eliminates the risk of missing a payment.
-
Significant Savings: If you can consolidate a 22% credit card debt into an 11% personal loan, you save thousands of dollars in interest over the life of the loan.
-
Credit Score Boost: A successful consolidation loan improves your credit utilization ratio (by paying off cards) and demonstrates responsible debt management, potentially boosting your score quickly.
The Red Flags: The Dangers that Compound Debt
Debt consolidation is a powerful tool, but it can be dangerous if mismanaged.
-
It Does Not Eliminate Debt: This is the biggest misconception. You are not erasing your debt; you are just moving it. If you continue spending, you will end up with more debt.
-
The Origination Fee Trap: Many loans come with significant origination fees (1-8% of the loan amount), which are deducted from the payout. This can negate your interest savings.
-
Ignoring the Root Cause: The most critical danger is that a consolidated loan does not fix the behavior that caused the debt (overspending, lack of emergency fund). Without addressing the root cause, you will be back in debt within a year.
Is Consolidation Right for You? The Decision Matrix
Before clicking “Apply” on Finance Shoot or any lender’s ad, assess your situation.
-
Yes, If: You have a stable income, a credit score high enough to qualify for a low interest rate, and you have stopped overspending.
-
No, If: Your income is unstable, your credit score is too low to get a significant interest rate reduction, or you are still using your credit cards for everyday purchases.
Debt consolidation can be a pivotal financial tool, but it is not magic. It is a powerful catalyst that requires a strong personal finance foundation. It offers clarity and savings, but only if you have the discipline to use those savings to pay off your debt faster—not to spend more. If you are ready to fix your spending habits and want to streamline your path to financial freedom, debt consolidation on Finance Shoot can be your ultimate game-changer. Otherwise, it is a danger zone you must avoid.