Forget Savings Accounts: Smarter Places to Park Your Emergency Fund in 2026
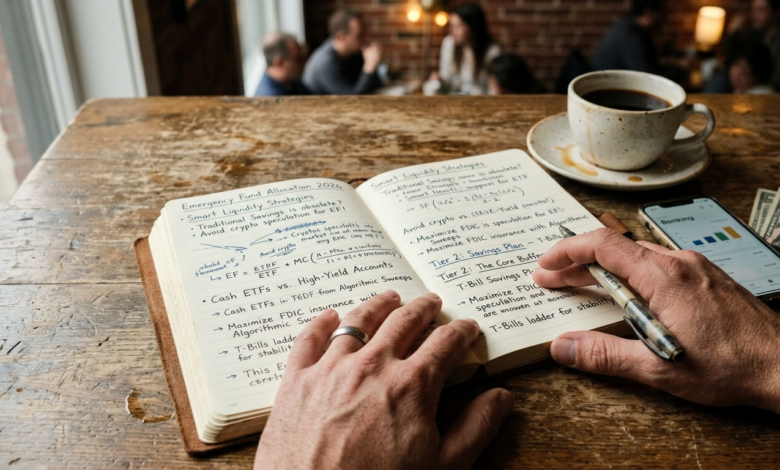
For decades, the golden rule of personal finance was simple: set aside three to six months of living expenses and let it sit safely in a standard bank savings account. But as we navigate the financial realities of 2026, that traditional advice is no longer just outdated—it is costing you money.
With shifting interest rates, the rise of decentralized and algorithmic yield platforms, and persistent structural inflation, “safe” cash can quickly become a depreciating asset. Today, optimizing your personal liquidity requires a strategic upgrade. Here is how modern wealth-builders are restructuring their emergency funds this year.
The Problem with “Traditional” Safety
Traditional brick-and-mortar savings accounts offer a sense of security, but their yields rarely keep pace with the real cost of living. In 2026, leaving significant capital idle in a legacy account means you are effectively accepting a negative real return after factoring in purchasing power loss.
To combat this, personal finance fluidly moves toward automated capital efficiency—ensuring that every dollar earmarked for emergencies is actively working, without sacrificing the immediate liquidity you need when life happens.
Dynamic Vehicles for Emergency Cash in 2026
If you want your cash to maintain its buying power while remaining accessible, consider these highly reliable, modern financial vehicles:
1. High-Yield Savings ETFs (Cash ETFs)
Instead of locking money into fixed-term certificates of deposit (CDs), retail investors are increasingly utilizing cash management ETFs. These funds invest directly in short-term government treasury bills and high-grade commercial paper.
-
The Benefit: They offer competitive, institutional-grade yields with the flexibility of being traded daily on major stock exchanges.
2. Algorithmic High-Yield Cash Accounts (FinTech)
The FinTech ecosystem in 2026 has matured significantly. Next-generation cash accounts now use predictive AI tools to automatically sweep your idle funds across a network of program banks. This setup maximizes your interest rate yield based on daily market shifts while keeping your money fully backed by FDIC (or regional equivalent) insurance.
3. Treasury Inflation-Protected Securities (TIPS) & Short-Duration Bills
For the conservative portion of your emergency fund (the funds you might not need in the next 30 to 60 days), rolling short-term Treasury bills (T-Bills) remains a powerhouse strategy. They are backed by the full faith of the government and currently offer some of the most resilient risk-adjusted returns for cash positions.
How to Segment Your 2026 Emergency Fund
The most effective liquidity strategy today is Tiering. You do not need instant, one-minute access to six months’ worth of expenses. Instead, break your protection fund into three distinct operational tiers:
| Tier | Purpose | Ideal Vehicle | Accessibility |
| Tier 1: Immediate Cash (1-2 Weeks of Expenses) | Instant ATM withdrawals, immediate digital transfers. | Local High-Yield FinTech Cash Account | Instant / Same Day |
| Tier 2: The Core Buffer (1-2 Months of Expenses) | Major unexpected bills (medical, auto repair, home maintenance). | High-Yield Cash ETFs or Brokerage Money Market Funds | 1 – 2 Business Days |
| Tier 3: Structural Safety (3+ Months of Expenses) | Extended income disruption or job loss coverage. | Rolling Short-Term T-Bills or Parametric Protection Products | 3 – 5 Business Days |
Key Mistakes to Avoid
-
Chasing Over-Hyped Crypto Yields: While decentralized finance (DeFi) offers attractive numbers, an emergency fund is not a speculative portfolio. Keep your protection capital strictly in regulated, transparent, and low-volatility vehicles.
-
Ignoring Liquidity Lock-ups: Avoid financial vehicles that penalize you for early withdrawal. If you cannot access the cash within 48 to 72 hours without a fee, it is an investment, not an emergency fund.
The Bottom Line: Personal finance in 2026 isn’t about taking unnecessary risks; it’s about eliminating unnecessary inefficiencies. By tiering your liquidity and leveraging modern cash management tools, you can keep your safety net fully intact while ensuring inflation doesn’t erode your hard-earned security.